Retirement Savings by Age: India + US Benchmarks 2026

By Tapabrata Biswas · Published September 16, 2026 · 16 min read
Researched with AI assistance, reviewed and edited by Tapabrata Biswas.
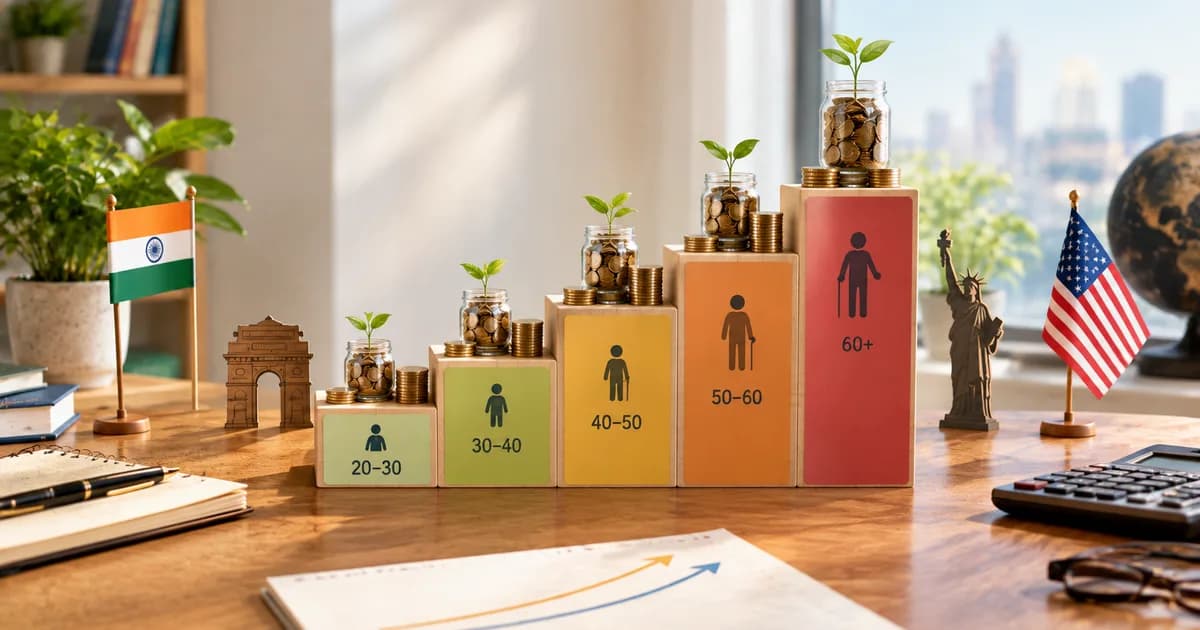
Two of the most-cited retirement benchmarks in the world disagree about age 40 by more than a year's salary, and neither page mentions the other exists.
Fidelity says hold 3x your salary. T. Rowe Price says 1.5x to 2.5x. Both publish their workings. Both are internally sound. They differ because they retire you at different ages and replace different shares of your income, and a reader who meets one number without the other has no way to know the disagreement is there.
Then the ladder crosses an ocean it was never built for.
What are the retirement savings benchmarks by age?
The benchmark most pages quote is Fidelity's: 1x your salary saved by 30, 3x by 40, 6x by 50, 8x by 60 and 10x by 67. Fidelity publishes it on its own site, in its own words: "Aim to save at least 1x your salary by 30, 3x by 40, 6x by 50, 8x by 60, and 10x by 67."
So it is real, and it is not folklore. What it is not is a fact about retirement. It is the output of a model, and the model is printed in a footnote.
| Age | Fidelity | T. Rowe Price | Ally | Empower | Guardian |
|---|---|---|---|---|---|
| 30 | 1x | 0.5x | 1x | 1x | 1x |
| 40 | 3x | 1.5x to 2.5x | 3x | 3x | 3x |
| 50 | 6x | 3.5x to 5.5x | 5x | 6x | 6x |
| 60 | 8x | 6x to 10.5x | 7x | 8x | 8x |
| 67 | 10x | 7.5x to 13x at 65 | none | 10x | 10x |
Three of those firms publish Fidelity's exact numbers as their own. Ally publishes something a full multiple lower at 50 and 60 with no basis stated. Vanguard, which holds a larger dataset than any of them, declines to publish a multiple at all.
Why do Fidelity and T. Rowe Price disagree?
Because they are answering the same question with different retirement ages and different income-replacement targets, and the multiple is whatever falls out of that. At 40, Fidelity's single number sits above the top of T. Rowe Price's entire range.
Fidelity's assumptions, from its own footnote: a "15% savings rate" starting "at age 25", a "retirement age of 67", the corpus replacing "45% of pre-retirement annual income" with Social Security covering the remainder, and "planning age through 93".
T. Rowe Price's, also published: retirement at 65, "investment returns before retirement are 7% before taxes", a savings path starting at "6% at age 25" and ramping "one percentage point each year" to 15%, spending in retirement reflecting "a 5% reduction from preretirement levels", and Social Security estimated "using the SSA.gov Quick Calculator".
Two years of retirement age and a different replacement target produce the gap. At 50 the spread runs from T. Rowe's 3.5x floor to Fidelity's 6x. On a $100,000 salary that is $250,000 of disagreement between two benchmarks a reader is likely to meet in the same afternoon.
Neither firm is wrong. The reporting is what fails, because a multiple quoted without its assumptions cannot be checked against your own situation.
The footnote that changes the number
Fidelity's 15% savings rate assumes you began at 25, and Fidelity says what happens if you did not. On its page about how much to save each year, the footnote reads: "For a starting age of 30 with no existing retirement savings and a retirement age of 67, the savings rate target increases to 18%. Similarly, the target increases to 23% for a starting age of 35 and a retirement age of 67."
Read that against the ladder. A 35-year-old starting from zero is not looking at 15% of income. They are looking at 23%, which is more than half as much again.
That footnote is on Fidelity's own site. It is missing from the pages that republish Fidelity's multiples, including Empower's and Guardian's, which carry the 1x to 10x ladder with no savings-rate caveat attached. The benchmark was built for someone who started early, and it gets handed to people who did not.
There is a second contradiction worth naming. Fidelity's 10x is engineered so the corpus replaces 45% of pre-retirement income, with Social Security doing the rest. Empower publishes the identical 10x while assuming replacement "between 70% and 80% of your pre-retirement income". The same multiple cannot deliver both.
Why the American ladder does not survive the trip to India
India's gross pension replacement rate is 38.9%. The United States reaches 73.2%. That single difference is why an imported multiple misleads.
The figures come from OECD pension models, reproduced in AMFI's August 2025 retirement whitepaper.
| Mandatory public | Mandatory private | Voluntary | Total | |
|---|---|---|---|---|
| India | 23.4% | 15.5% | none counted | 38.9% |
| United States | 39.1% | none | 34.1% | 73.2% |
| OECD average | 42.3% | not split out | not split out | over 50% |
AMFI states the reason plainly: "Lack of penetration and development of the voluntary pension system does not add any money to the replacement rate in India."
Coverage tells the same story. Per the same OECD data, "Only 27.2% of the population aged 15-64 is covered under mandatory pension schemes" in India, and "only 54.9%" of the labour force, against OECD averages of 75.8% and 95.1%.
Now recall what Fidelity's 10x is for. It covers 45% of income, because Social Security covers the rest. Move that multiple to a country whose entire system replaces 38.9%, and the part the corpus must carry is much larger. The number should go up, not stay the same.
Our guide to the Indian retirement corpus works through what that means for the total target, including why Indian withdrawal-rate research lands near 3.0% to 3.5% where the American rule of thumb says 4%.
What Indian pages actually publish
Two of the Indian pages ranking on this question print the American ladder with no source and no adjustment.
Tata Capital Moneyfy lists 1x of total salary at 30, 3x at 40, 6x at 50 and 8x at 60. Those are Fidelity's numbers, digit for digit. The page cites nobody, not Fidelity, not EPFO, not PFRDA, not RBI. Its author is credited as "admin". It sells an investment app.
HDFC Life states that "the ideal corpus for retirement should be 7-8 times your salary by the start of your 60's", again with no derivation and no sources, on a page selling pension plans and annuities. The genuinely different idea on that page is its 30X rule, which sizes the corpus against annual expenditure and not against salary, and expenditure is the better anchor in a country where the pension backstop is thin.
Neither page mentions Indian inflation, tax on withdrawals, or the missing state pension.
Is there any Indian benchmark by age?
We looked at PFRDA, SEBI, RBI, AMFI and NISM, and none of them publishes one. That absence is the finding, so it is worth being precise about where we looked.
PFRDA's socio-economic study of NPS subscribers is the likeliest place such a number would live. It analyses 14.45 lakh subscribers and breaks them down by gender, age group, education, occupation, income and region. Its age table shows where Indians open NPS accounts: 6% aged 18 to 25, 33% aged 26 to 35, 31% aged 36 to 45, 21% aged 46 to 55, 7% aged 56 to 60.
What it does not contain is any figure for what those subscribers have accumulated. The word corpus appears once in the document, in the definition of what NPS is. The study covers enrolments to 2020-21, so it is five years old.
NISM, the institute SEBI established, goes further and argues against the whole idea of a universal benchmark. Its retirement piece warns about "amplified numbers propagated on social media" and says "the estimate has to be in tune with your income and expense level". Its method works from expenses: a monthly expense of ₹1,00,000 implying a corpus near ₹1.6 crore, ₹3,00,000 implying ₹4.8 crore, at 5% inflation and a 4.76% net real return.
So the pattern across the Indian market is a clean split. The regulator, the regulator's institute and the industry body all decline to publish a by-age multiple. Product companies publish one anyway, and it is American.
What Indians actually have, where anyone has measured it
No by-age accumulation figure for India exists in any source we could reach. Every measured number is a national aggregate or a snapshot at exit.
The most striking one comes from EPFO. Business Standard, reporting EPFO's own statements in July 2026, says "about 48.7 per cent of EPF members have PF balance of only between ₹10,000 and ₹20,000 at the time of final settlement". That is a figure attributed to the organisation and not published by it directly, so treat it as reported.
Set it beside a benchmark of 8x salary by 60 and the distance is the whole story.
PFRDA's own study supplies the other half. Across five years, "Average 11% of the total accounts opened got frozen", and among the reasons an NPS account freezes is "non-contribution of Rs 1000 in a year". Roughly one in nine accounts opened stopped, a good share of them over a thousand rupees across twelve months.
Those two numbers describe the same country the 8x benchmark is being sold into. Our explainers on the National Pension System and the Employees' Provident Fund cover how each actually works.
Average, median, and which number is being quoted
When a page says "average retirement savings by age", ask which dataset and which account. At least four circulate, and they are not comparable.
| Dataset | Under 35 or nearest band | Median given? |
|---|---|---|
| Survey of Consumer Finances, retirement accounts | $49,130 | Yes, $18,880 |
| Survey of Consumer Finances, bank savings | $20,540 | Yes, $5,400 |
| Vanguard defined contribution plans | 35-44: $91,281 | Yes, $35,537 |
| Fidelity 401(k) book | 35-39: $81,600 | No |
| Empower app users | 30s: $296,560 | Yes, $99,919 |
The first two rows come from the same survey and differ by more than double, because one counts retirement accounts and the other counts money in bank savings. Pages quote both as "average savings by age" without saying which.
The Empower row is self-selected users of a wealth-tracking app. Its figure for people in their 20s is around 5.7 times Fidelity's average for ages 25 to 29, presented in the same visual style as national survey data.
And the average is the wrong statistic anyway. A small number of large balances drags it upward, which is why the median sits so far below: $49,130 against $18,880 on the same survey line. Of the major pages, only Guardian states the skew in words, and Fidelity, Edward Jones and Ally publish no median at all.
What this post deliberately does not cover
No number here is a target for you. Every multiple above is one firm's modelling output under its own published assumptions, and the assumptions are the part that has to match your situation, not the multiple.
This does not cover which instruments to hold at any age, how to split between EPF, NPS, mutual funds or anything else. That is portfolio advice and it turns on your tax position, your dependants and your capacity to absorb a fall. For India, a SEBI-registered investment adviser is the right person; in the US, a CFP.
Three limits in the research are worth stating. Investopedia's page on this subject could not be fetched across repeated attempts. Our view of the Indian search results is partial, because the tools available to us read the US results page. And two widely-quoted Indian survey figures for an "ideal" retirement corpus were traceable only to secondary coverage, so they are absent here rather than repeated.
Frequently asked questions
How much should I have saved for retirement by age? The most-cited benchmark is Fidelity's: 1x your salary saved by 30, 3x by 40, 6x by 50, 8x by 60 and 10x by 67. Fidelity publishes it on its own site along with the assumptions behind it, which are a 15% savings rate starting at age 25, retirement at 67, and the corpus replacing 45% of pre-retirement income with Social Security covering the rest. Those assumptions matter more than the multiple, because change any one of them and the number moves. T. Rowe Price models the same question differently and gets 1.5x to 2.5x at 40 against Fidelity's 3x.
Do Fidelity and T. Rowe Price agree on retirement savings by age? No, and the gap is wide enough to matter. At age 40 Fidelity publishes 3x salary while T. Rowe Price publishes a range of 1.5x to 2.5x, so Fidelity's figure sits above the top of T. Rowe's entire range. At 50 Fidelity says 6x and T. Rowe says 3.5x to 5.5x. On a $100,000 salary the distance between T. Rowe's floor and Fidelity's number at 50 is about $250,000. The reason sits in the assumptions each firm publishes: Fidelity retires you at 67 and has the corpus replace 45% of income, while T. Rowe retires you at 65 and assumes a 7% pre-tax return with spending 5% below pre-retirement levels.
Does the 15% savings rate really get you to 10x by 67? Only if you started at 25, and Fidelity says so itself in a footnote. Its page on how much to save each year states that for a starting age of 30 with no existing retirement savings and a retirement age of 67, the savings rate target increases to 18%, and that the target increases to 23% for a starting age of 35. So a 35-year-old beginning from zero needs roughly half as much again as the headline figure. Pages that republish Fidelity's 1x to 10x ladder almost never carry that footnote, which is how a benchmark built on an early start gets handed to people who did not have one.
Do the American retirement benchmarks work in India? Not without adjustment, because they assume a state pension India does not provide. OECD figures published in AMFI's August 2025 retirement whitepaper put India's gross pension replacement rate at 38.9%, made up of 23.4% mandatory public and 15.5% mandatory private, against an OECD average above 50%. The United States reaches 73.2% once voluntary pensions are counted, and AMFI notes that India's voluntary pension system adds nothing to its rate. Fidelity's 10x is calibrated so the corpus covers 45% of income and Social Security covers the rest. Transplant that multiple to a country where the equivalent backstop is far smaller and the arithmetic no longer holds.
Is there an Indian benchmark for retirement savings by age? No institutional one that we could find. We checked PFRDA, SEBI, RBI, AMFI and NISM. PFRDA's socio-economic study of NPS subscribers breaks its 14.45 lakh subscribers down by age group, gender, education, occupation and income, and contains no corpus-by-age figures at all. NISM, the institute SEBI established, publishes a retirement piece that gives no multiple and argues against universal benchmarks, warning about amplified numbers on social media and saying the estimate has to be in tune with your income and expense level. The by-age multiples circulating in India come from product companies copying the American ladder.
What is the average retirement savings by age, and why do the numbers disagree? Because at least four different datasets circulate under the same label and they measure different things. Two come from the same Federal Reserve Survey of Consumer Finances and differ by more than double, because one counts retirement accounts and the other counts bank savings. Vanguard reports its own plan participants, Fidelity reports its own 401(k) book, and Empower reports users of its wealth-tracking app, whose figures run far above everyone else's. The bigger problem is the average itself, which a small number of large balances pulls upward. Where the median is published alongside it, the gap is wide: the Survey of Consumer Finances puts under-35 retirement accounts at an average of $49,130 against a median of $18,880.
In summary
The ladder is real, Fidelity publishes it, and it comes with a footnote saying a 35-year-old starting from zero needs 23% of income where the headline says 15%. The firms that reprint the ladder mostly drop the footnote, and the firm with the largest dataset declines to publish a ladder at all.
In India the same numbers arrive stripped of even more. A country whose pension system replaces 38.9% of earnings is being handed a benchmark built for one that replaces 73.2%, by companies selling the products that would close the gap. Meanwhile roughly one in nine NPS accounts stops over a thousand rupees a year.
The useful move is not finding your age in a table. It is asking what any given multiple assumes about when you started, when you stop, and what else pays you after that. Our retirement corpus guide runs those assumptions for India, and the beginner's roadmap puts retirement in the order it belongs.
Sources
All pages below were checked on 16 September 2026.
- Fidelity Investments, How much do I need to retire? (the 1x to 10x ladder and its assumption footnote, dated 14 February 2025), fidelity.com
- Fidelity Investments, How much money should I save each year for retirement? (the 18% and 23% savings-rate footnote, dated 8 June 2026), fidelity.com
- T. Rowe Price, You're age 35, 50, or 60: How much should you have saved for retirement by now? (the ranges and the full assumption list, April 2026), troweprice.com
- Association of Mutual Funds in India, Mutual Funds: A Bridge to Financial Freedom and Viksit Bharat, August 2025 (pension replacement rates and coverage, from OECD pension models), amfiindia.com
- Pension Fund Regulatory and Development Authority, Socio-economic characteristics of NPS subscribers (all citizen model) (age-group enrolment table and the 11% frozen-account figure, covering 2016-17 to 2020-21), pfrda.org.in
- National Institute of Securities Markets, Your Retirement Kitty: How Much Is Enough? by Joydeep Sen, 22 December 2025 (the expense-based method and the case against universal benchmarks), nism.ac.in
- Business Standard, Low retirement savings prompted minimum PF balance rule, says EPFO, 15 July 2026 (the 48.7% figure, attributed to EPFO), business-standard.com
- Vanguard, Saving for retirement (average and median balances in its own defined contribution plans), investor.vanguard.com
- Guardian Life, Average Retirement Savings by Age (Survey of Consumer Finances averages and medians, and the skew caveat, last updated 28 May 2026), guardianlife.com
- Experian, Average Savings by Age in America (the same survey measured on bank savings, not on retirement accounts, 15 May 2026), experian.com
- Empower, Average retirement savings by age (figures drawn from Empower Personal Dashboard users, September 2026), empower.com
- HDFC Life, How Much Should I Have Saved by 60 For Retirement? (7 to 8 times salary and the 30X rule, 9 June 2026), hdfclife.com
You might also like
The same question, asked of more than thirty ranking pages, returns answers from 58 lakh to 21.8 crore. The spread is not disagreement about India. It is one assumption.
17 min read
NPS entry now runs to age 85, and non-government exits need only 20% annuity since December 2025. What the new tax regime allows, and what it takes away.
17 min read
What is EPF? The 8.25% FY 2025-26 interest rate, the 12% + 12% contribution split, the new EPF Scheme 2026 withdrawal rules, and the tax treatment explained.
14 min read